

Epic boom: ~40% of Sun Belt apartments sold post-COVID
Case study: $31M → $111M syndicator buy → $77M REO sale
The fulcrum: Syndicators (e.g., Trinity Investors)
The fees: Trinity pulled in $50M of placement revenue during 2022
The leverage: Debt funds (e.g., Blackstone, Walton Street)
The back leverage: CRE-CLOs (vs. CDOs, strong performance so far)
One more thing: Freddie delinquencies approaching GFC levels
Scott Everett of S2 explaining his early days of apartment investing in 2012:
“At 5:00 AM I'd get up, I'd go up there. And I lived that site every single day of my life. I remember I was buying baby powder because June, that was when all the students were moving out. And I'm up there every single day punching out units, getting them turned as quickly as we could in the dead of the heat. But it was the best thing for me, and the best education, because I learned how everything plays out on site. I figured out how all the tenants work. I figured out what you get paid for on the value-add improvements. I figured out where you can cut corners for cost purposes and truly the value add. And I figured out how to manage an asset on site from the ground up.”
Everett rode the wave of falling cap rates and interest rates through the post-COVID recovery, but S2’s situation (and that of all apartment investors) shifted meaningfully when interest rates increased. Then S2 and its syndicator, Trinity Investors, pitched a lifeline plan to investors.
If they could just convert the short-term equity and debt to long-term equity and debt, they would have time to grow their way out without the imminent threat of loan maturities, paydowns, and rate cap renewals.
Trinity’s pitch to investors highlighted seemingly attractive returns:
“22-27%+ IRR. 2.5-3.1x multiple. Five years.”
But by 2026, Trinity’s tone was much more alarming:
“Equity investors should expect a full loss of capital.”
This story isn’t about S2 or even Trinity specifically. This is a look back at the pipes that flooded capital into a relatively small corner of the market, resulting in GFC-like equity destruction. The backstory is about the debt that financed these transactions. We dive into all of this below and uncover context that explains what happened and what is not happening (e.g., debt implosions).
Let's follow the dollars…
Four years after “survive till ‘25” emerged as an industry mantra, we have an updated scorecard for multifamily investors:
~40% of apartments traded during the post-COVID rebound.
~25% of these trades were Class B properties.
Class B cap rates moved from 6-7% to ~4%.
Pro formas were built on hopes, dreams, and floating-rate debt.
Then the music stopped.
Equity is being destroyed at a GFC pace.
Lenders are mostly fine.
Maybe real estate capital markets finally got it right.
Coverage of the multifamily reset usually falls into a few familiar flavors: (i) the sky is falling, syndicators are the new subprime, contagion is coming, or (ii) lenders are hiding problems by “kicking the can,” or (iii) nothing to see here.
These talk tracks miss the point. The truth is more complicated.
…and much more interesting.
A truly unique multifamily boom
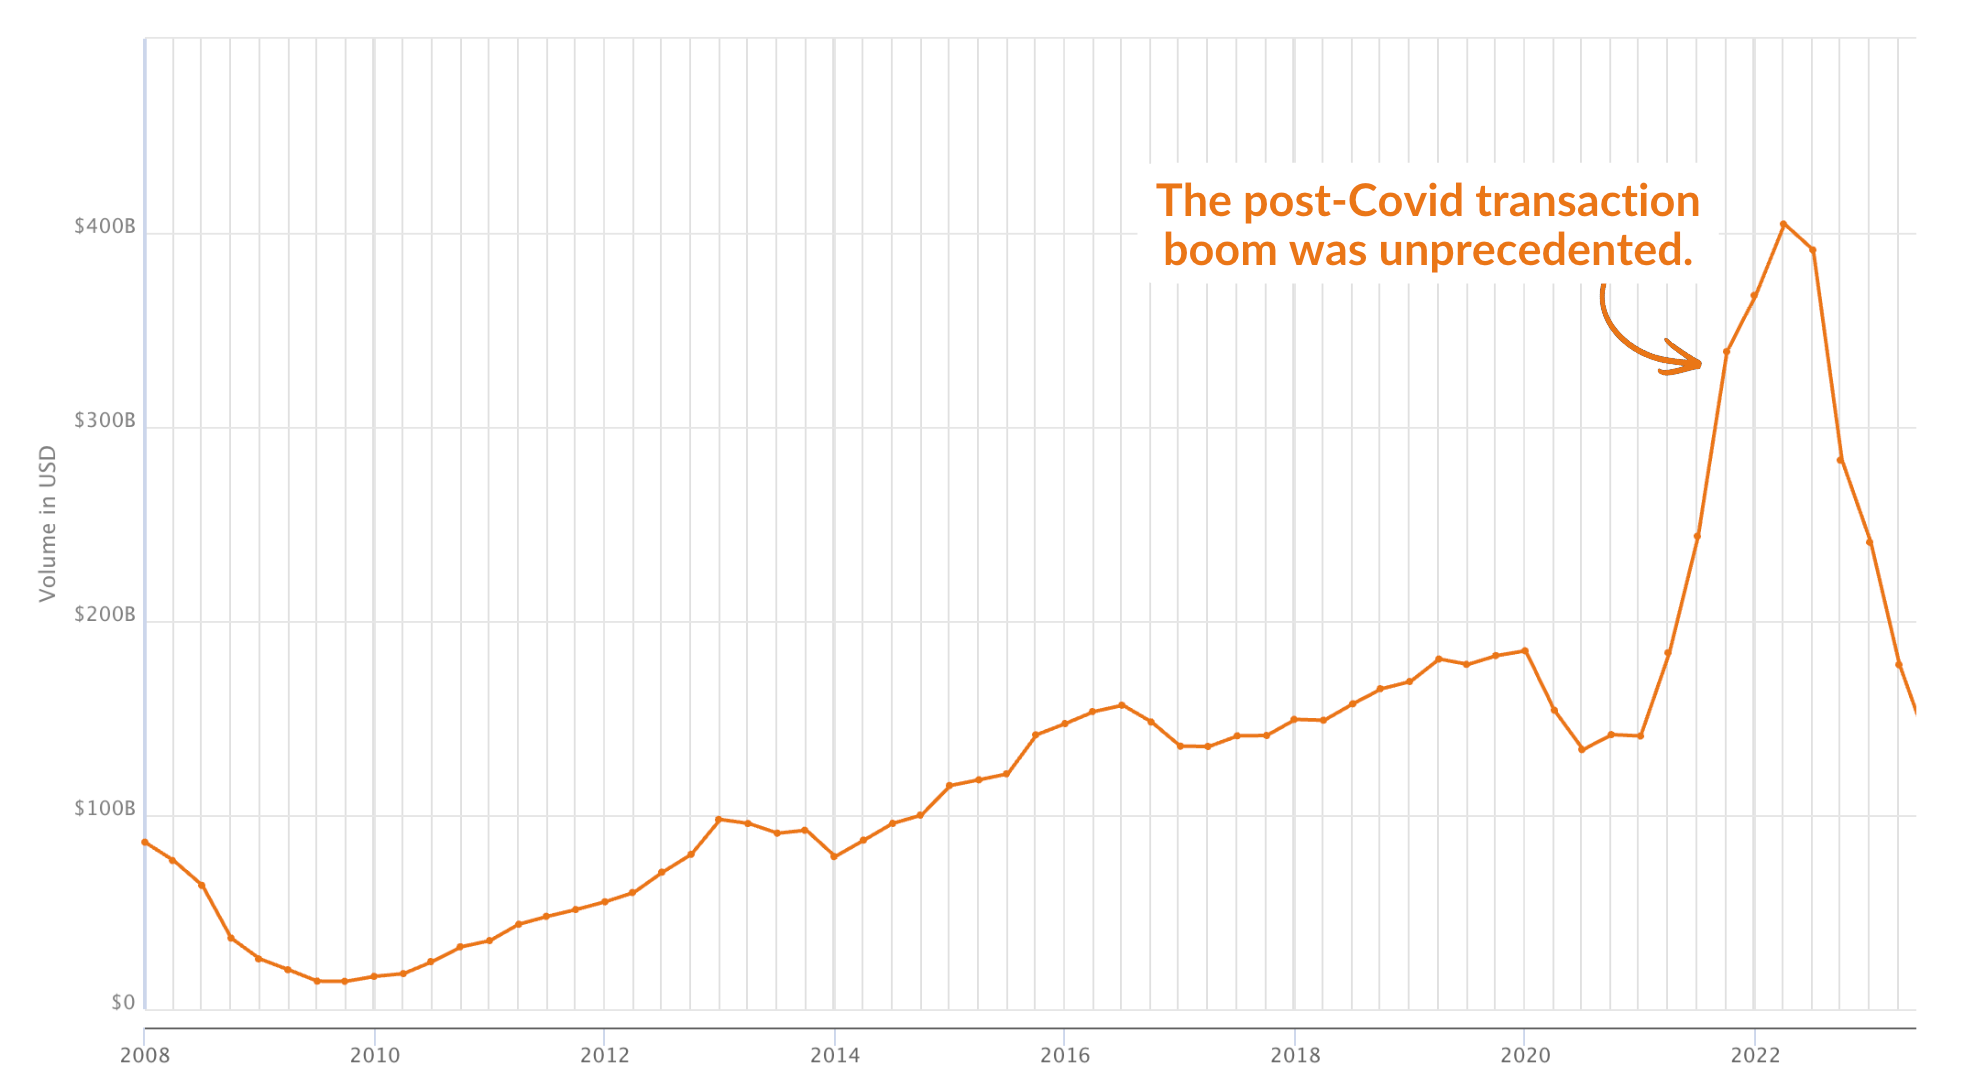
It’s easy to lose sight of how atypical the post-COVID transaction boom was for the multifamily market. Good luck finding another curve that looks like this:
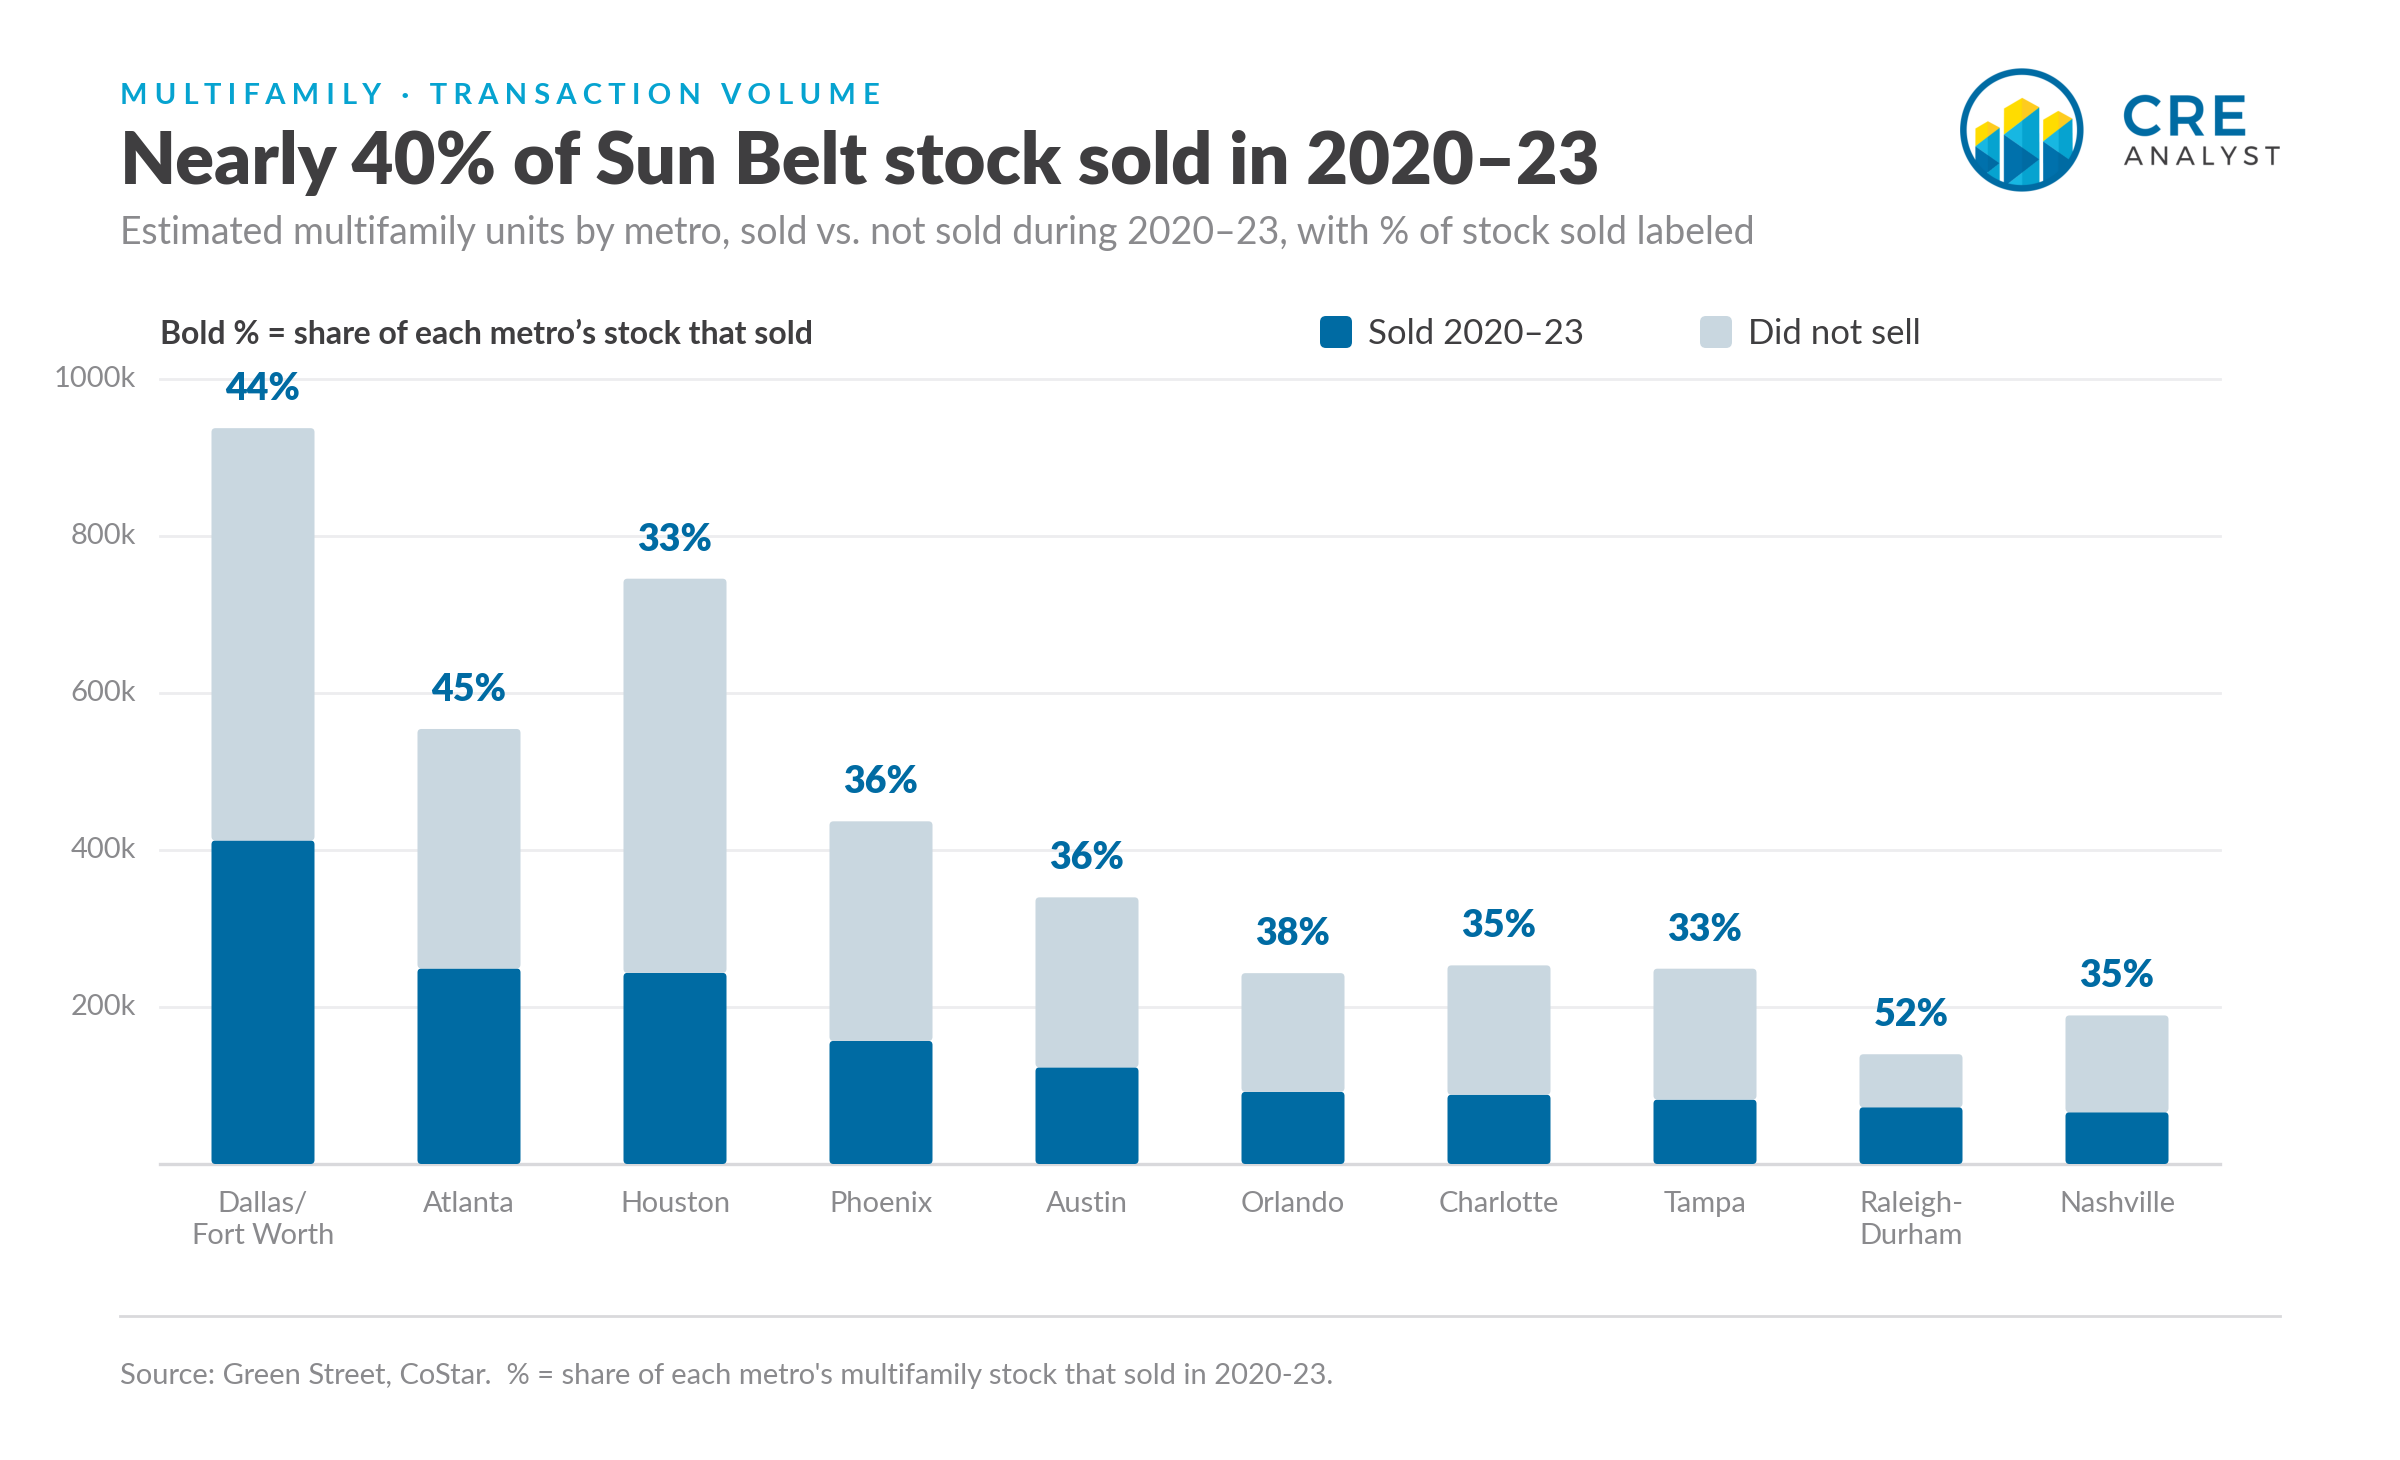
But how much of the total apartment stock traded during that window? Our best guess: about 40% in the Sun Belt markets, which hosted most of the action.
This transaction boom was fueled by a lot of debt…
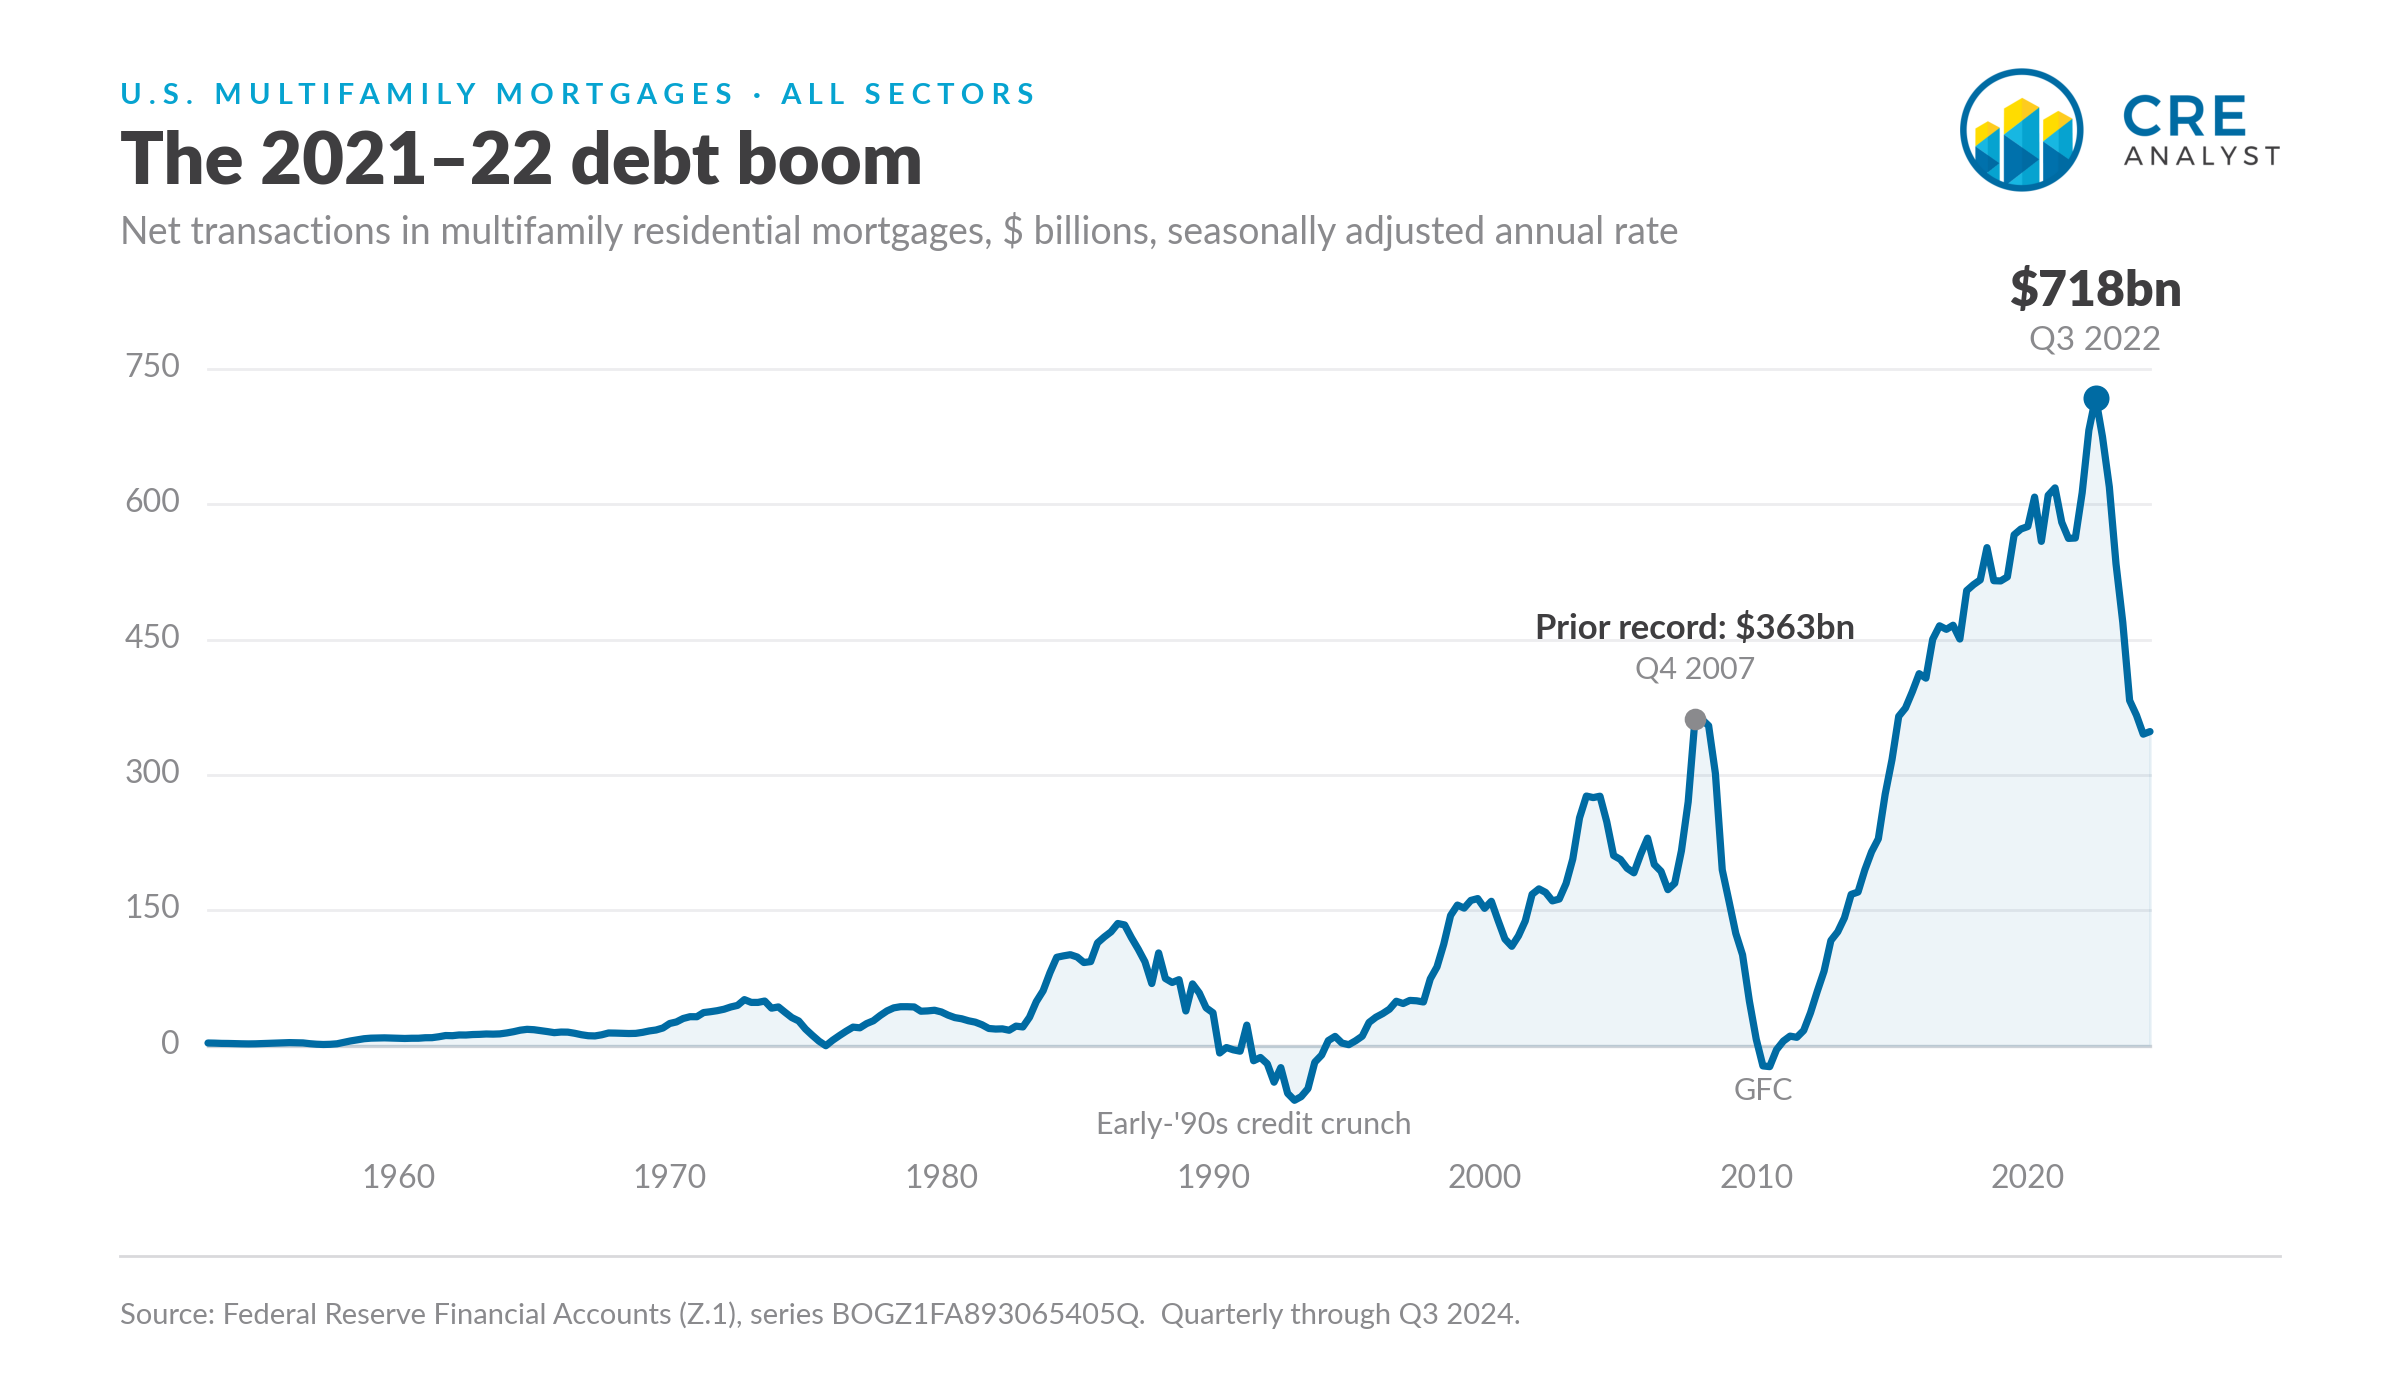
…which created one of the most lucrative short-term windows in history for multifamily sponsors.
Multifamily Sponsors
The result was two things happening at once: the equity in these deals is getting destroyed at a GFC pace, while the debt that financed them is holding up far better than almost anyone predicted. We’ll trace both, starting with the equity and working down through the debt.
S2
In early 2024, we found some interesting SEC filing activity relating to S2 and Trinity Investors. Back then, we summarized S2 and syndicators’ struggles as follows:
“The apartment syndicator narrative is well-known. A handful of apartment buyers led a historic surge in floating-rate financed purchases at all-time-high prices during the COVID rebound. Now they're struggling. S2 was in the mix, buying $3B+ coming out of the pandemic, mostly with floating-rate debt.”
CRE Analyst, March 2024
Here’s what we speculated at the time was going on:
“It's possible that S2 just created a perpetual vehicle for its existing investments. Converting investors to an open-ended vehicle would provide S2 with a runway to secure relatively favorable financing. If this is what happened, S2 just showed other syndicators how to survive until '25.”
CRE Analyst, March 2024
And here’s what S2 and its syndicator (Trinity Investors) told investors at the time:
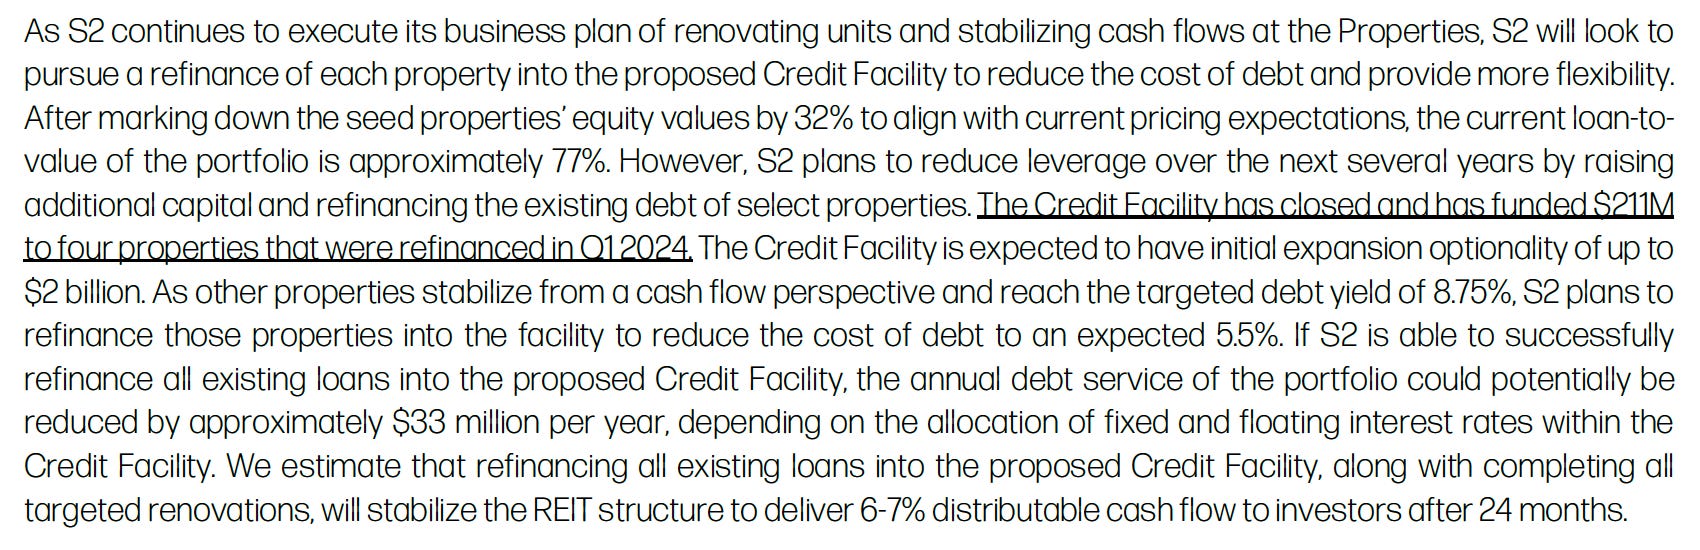
Some S2 investors would not have liked this move, any more than an institutional LP likes hearing about a closed-end fund converting to a continuation vehicle. Why? It’s not what LPs signed up for, and valuation without arm’s-length trades is a guessing game.
Those challenges undoubtedly existed at S2, but the REIT vehicle at least provided a potential sustainable path, as long as it led to sustainable debt. As outlined above in a Trinity memo, the move could have saved ~$33 million a year.
Fast forward to now, and it looks like S2’s open-ended vehicle is under stress, with Trinity reportedly warning investors, “equity investors should expect a full loss of capital.”
If the REIT’s investors are getting warnings about a complete wipeout, the cornerstone financing must have gone away.
Syndicated equity
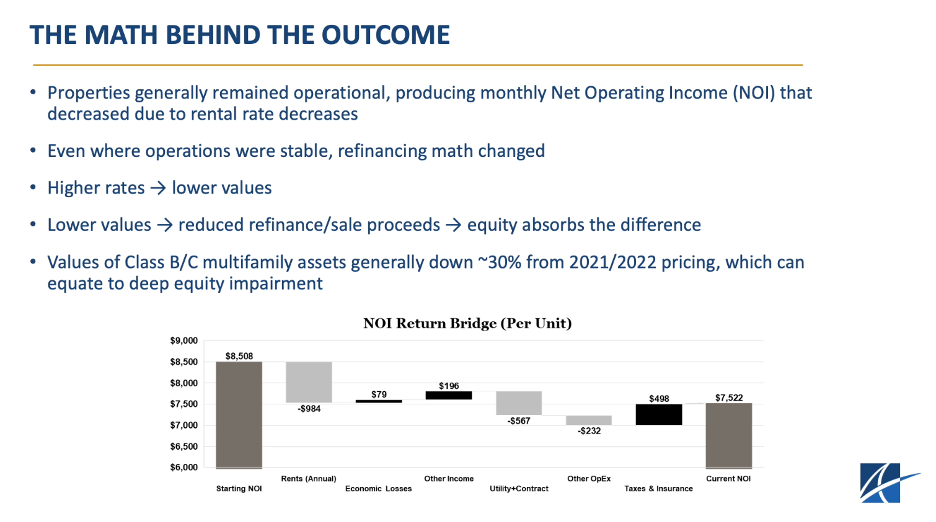
Once the post-COVID pop slowed and the Fed increased interest rates, syndicators and their sponsors faced problems from all sides. Rents stalled, expenses took off, borrowing costs spiked, and values plunged.
Here’s how Trinity Investors, one of the largest syndicators of apartment deals coming out of COVID (and a big funnel for S2), explained the shift to investors:
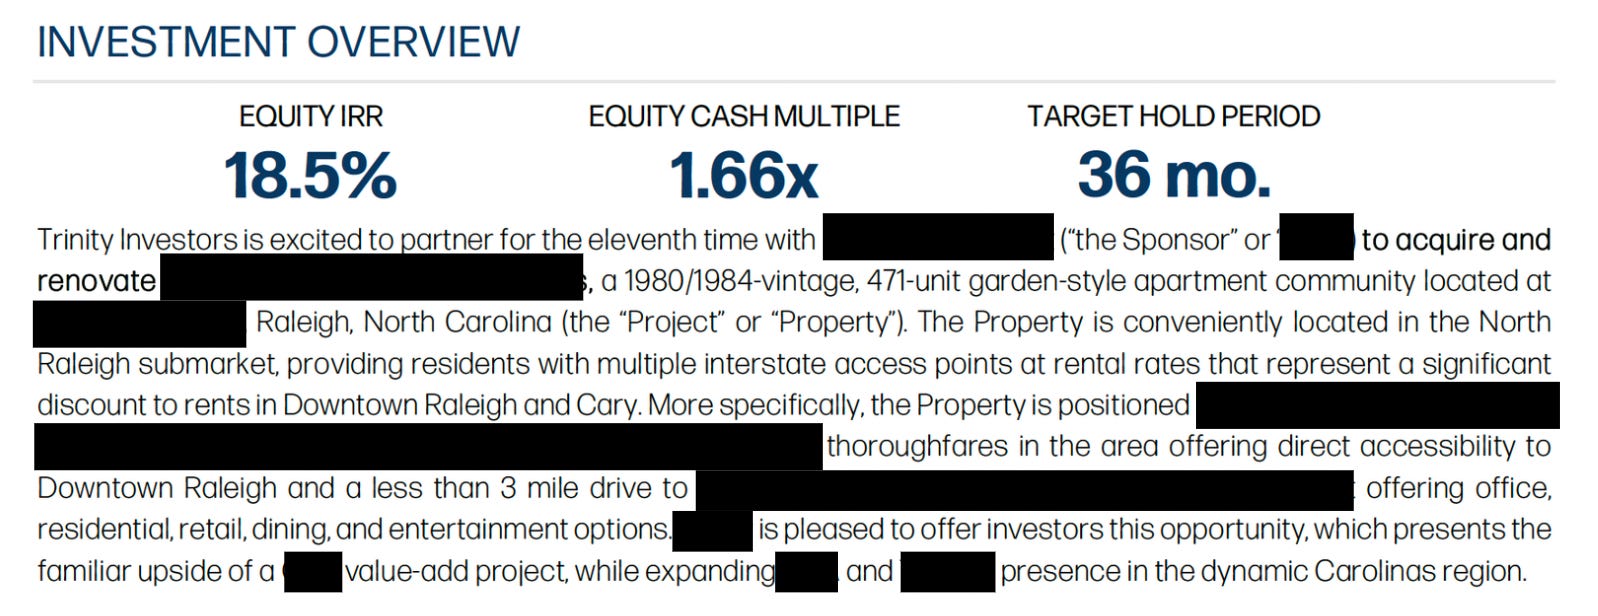
Sample Trinity deal
A sample deal that we profiled in a recent deep dive (not an S2 deal):
In early 2022, one of the largest syndication partnerships bought a 471-unit complex built in the early 1980s for $111 million (~$236,000 a door). The sponsor’s plan was to invest ~$12,000 a door into the property, raise rents, then refinance the loan or sell, generating 18%+ IRRs to investors.
Although the property traded two years earlier for $66 million, the sponsor justified an $111 million purchase price (~3% cap rate) with a business plan that called for growing NOI from $3.4 million to $6.8 million over three years.
This plan generated great returns to investors on paper:
Following the dollars of this deal over the last ten years…
2016: Local operator buys for $31 million at a 5.75% cap rate
2020: Regional value-add operator buys for $66 million at a 4.75% cap rate
2022: Syndicator-backed sponsor funds portfolio acquisition with an allocated price of $111 million to this deal at a 3.1% cap rate
2024: Benefit Street Partners forecloses on the asset at a mark of $88.5 million (likely the loan balance)
2026: Local operator purchases the property for $76.6 million with seller financing from the seller who previously foreclosed on the asset
According to SEC filings, Trinity raised $29.9M for this deal from 280 investors and pulled in ~$2M in placement fees. Although this deal had some unique components, it was not an anomaly. There were many syndicated deals like this.
More the rule than the exception
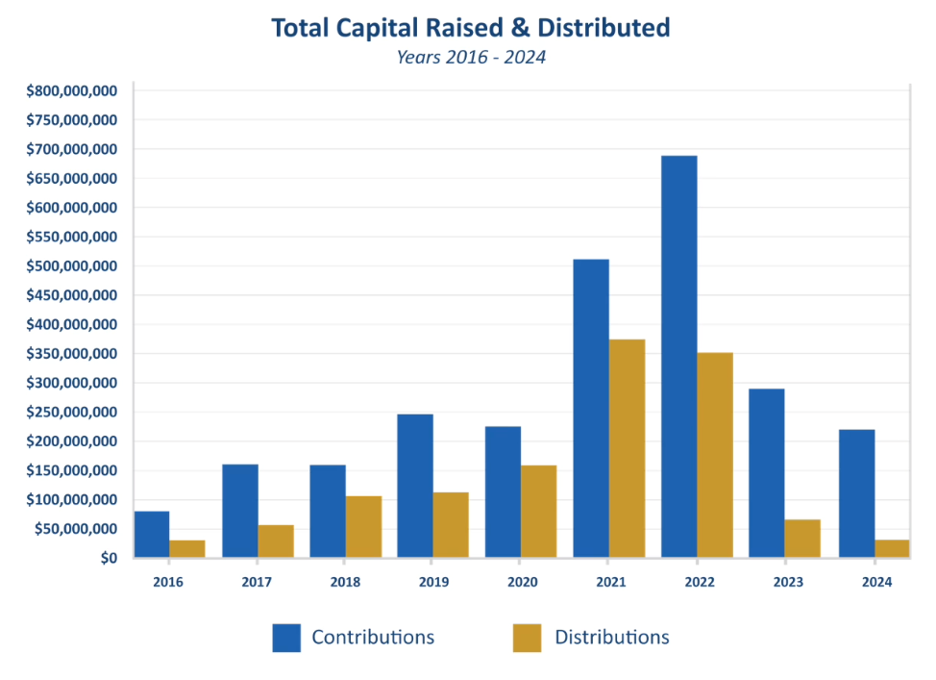
Eyeballing the chart below from 2025, it looks like Trinity funneled $1.5-2 billion (gross) and ~$750 million (net, after sales) between 2020 and 2023.
Placement fees
Wait, Trinity got $2 million in placement fees on a deal that went sideways and would be foreclosed on within two years?
Where’d that $2 million go? Good question…
Trinity has a related company that works with financial advisors and high-net-worth individuals on syndications. That firm is called TPEG Securities.
Here is the income statement of TPEG Securities for 2022:
